
PERSPECTIVE: EdTech Startups in Connecticut’s Educational Technology Ecosystem
/
There is a need to incorporate the startups into the EdTech ecosystem in a more meaningful way.
Read MoreThere is a need to incorporate the startups into the EdTech ecosystem in a more meaningful way.
Read MoreIn a settlement described as "the most significant engagement to date by state attorneys general involving a national bank without a federal law enforcement partner, Connecticut Attorney General George Jepsen announced that Wells Fargo Bank N.A. will pay $575 million to resolve claims that the bank violated state consumer protection laws by (1) opening millions of unauthorized accounts and enrolling customers into online banking services without their knowledge or consent, (2) improperly referring customers for enrollment in third-party renters and life insurance policies, (3) improperly charging auto loan customers for force-placed and unnecessary collateral protection insurance, (4) failing to ensure that customers received refunds of unearned premiums on certain optional auto finance products, and (5) incorrectly charging customers for mortgage rate lock extension fees.
Connecticut served on a multistate investigation leadership and negotiating team, along with the attorneys general of Arizona, Iowa and Pennsylvania. Connecticut's share of the settlement is $5,242,279, which will be deposited into the state's General Fund.
Through this settlement with all 50 states and the District of Columbia, the company will also create a consumer redress review program through which consumers who have not been made whole through other remediation programs already in place can seek to have their inquiry or complaint reviewed by an escalation team for possible relief, officials said.
"Wells Fargo engaged in conduct that violated the public's trust and ran afoul of state laws," said Attorney General Jepsen. "This settlement resolves Connecticut's consumer protection claims against the bank and creates an important avenue for Connecticut consumers seeking redress for the bank's improper conduct. I'm proud of the strong, bipartisan work of the states in this investigation that has helped bring this matter to a close."
As part of its settlement with the states, Wells Fargo has agreed to implement within 60 days a program through which consumers who believe they were affected by the bank's conduct, but fell outside the prior restitution programs, can contact Wells Fargo to be reviewed for potential redress. Wells Fargo will create and maintain a website for consumers to use to access the program and will provide periodic reports to the states about ongoing restitution efforts.
According to the Attorney General's office, Wells Fargo has identified more than 3.5 million accounts where customer accounts were opened, funds were transferred, credit card applications were filed, and debit cards were issued without the customers’ knowledge or consent. The bank has also identified 528,000 online bill pay enrollments nationwide that may have resulted from improper sales practices at the bank. In addition, Wells Fargo improperly submitted more than 6,500 renters insurance and/or simplified term life insurance policy applications and payments from customer accounts without the customers’ knowledge or consent.
The states alleged that Wells Fargo imposed aggressive and unrealistic sales goals on bank employees and implemented an incentive compensation program where employees could qualify for credit by selling certain products to customers. The states further alleged that the bank's sales goals and the incentive compensation program created an impetus for employees to engage in improper sales practices in order to satisfy such sales goals and earn financial rewards. Those sales goals became increasingly harder to achieve over time, the states alleged, and employees who failed to meet them faced potential termination and career-hindering criticism from their supervisors.
The states also alleged that Wells Fargo improperly charged premiums, interest, and fees for force-placed collateral protection insurance to more than two million auto financing customers, despite evidence that the customers’ regular auto insurance policy was in effect, and despite numerous customer complaints about such unnecessary placements. Wells Fargo has agreed to provide remediation of more than $385 million to approximately 850,000 auto finance customers. The remediation will include payments to over 51,000 customers whose cars were repossessed.
Additionally, the states alleged that Wells Fargo failed to ensure that customers received proper refunds of unearned portions of optional Guaranteed Asset/Auto Protection (GAP) products sold as part of motor vehicle financing agreements. As a result, the bank has agreed to provide refunds totaling more than $37 million to certain auto finance customers.
Finally, the states alleged that Wells Fargo improperly charged residential mortgage loan consumers for rate lock extension fees even when the delay was caused by Wells Fargo, a practice contrary to the bank’s policy. Wells Fargo has identified and contacted affected consumers and has refunded or agreed to refund over $100 million of such fees.
It is the latest major settlement involving government action against Wells Fargo practices.
Wells Fargo has previously entered consent orders with federal authorities – including the Office of the Comptroller of the Currency (OCC) and the Consumer Financial Protection Bureau (CFPB) – related to its alleged conduct. Wells Fargo has committed to or already provided restitution to consumers in excess of $600 million through its agreements with the OCC and CFPB as well as through settlement of a related consumer class-action lawsuit and will pay over $1 billion in civil penalties to the federal government. Additionally, under an order from the Federal Reserve, the bank is required to strengthen its corporate governance and controls, and is currently restricted from exceeding its total asset size.
More information on the redress review program, including Wells Fargo escalation phone numbers and the Wells Fargo dedicated website address for the program will be available on or before February 26, 2019. Consumers with questions about the redress program can contact the Office of the Attorney General's Finance Department at 860-808-5270.
Connecticut’s Insurance Department has issued its 2018 Consumer Report Card on Health Plans in Connecticut, providing consumers with an updated snapshot of 12 health carriers in the Connecticut marketplace. The goal: to help consumers make informed choices when choosing a health plan.
“The Department’s annual Report Card is designed to deliver side-by-side comparisons of health carriers across a variety of quality measures, including coverage for mental health and substance abuse treatment,” Commissioner Katharine L. Wade said recently. The analysis includes health claims, mental healthcare, pregnancy coverage and preventative care, and reviews the reasons cited in instances of denial of coverage. 
Among the trends identified in the latest annual report care are:
The 72-page data-filled report card also notes that there was an increase in the number of primary care providers, specialists and pharmacies participating in health plan networks. There was a decline in the number of participating hospitals, officials indicated, but attributed it “primarily due to consolidations in the industry and not facilities closing.”
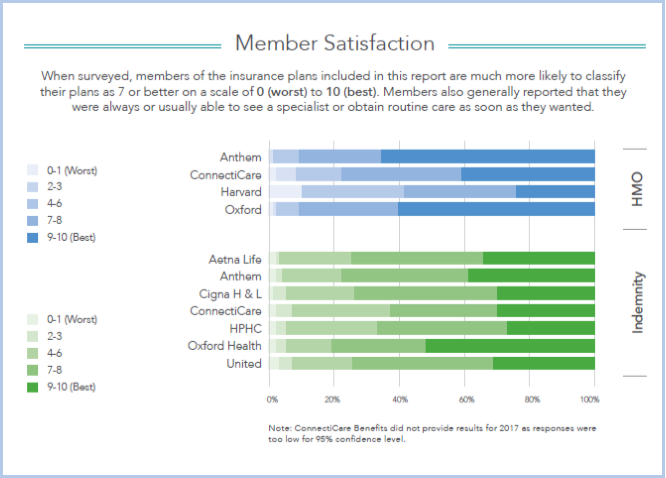
Customers surveyed said they were always or usually able to see a specialist or get routine care as soon as they wanted. The enrollment breakdown in Connecticut is lopsided. Among HMO's, Anthem has 81% of the market, ConnectiCare 17%, Oxford 2%. Among indemnity enrollments, Anthem has 42%, followed by Aetna's 20%, CIGNA's 19%, United's 7% and ConnectiCare's 5%.
The report card, issued this fall, includes “terms” that consumers should know, a series of frequently asked questions and answers, and results of a member satisfaction survey for HMO’s Anthem, ConnectiCare, Harvard Pilgrim and Oxford Health. Indemnity insurers Aetna Life, Anthem, CIGNA, ConnectiCare, Harvard Pilgrim, United Health and Oxford Health also had members surveyed on a range of “satisfaction” queries.
This report includes three years of data, where available, to be informative for consumers, officials said. The data utilized was through 2017.
The mission of the Connecticut Insurance Department is to protect consumers through regulation of the industry, outreach, education and advocacy. The Department recovers an average of $4 million yearly on behalf of consumers, according to officials, and regulates the industry by ensuring carriers adhere to state insurance laws and regulations and are financially solvent to pay claims.
Each year, the Department returns an average of $100 million a year to the state General Fund in license fees, premium taxes, fines and other revenue sources to support various state programs, including childhood immunization. The Department’s annual budget is funded through assessments from the insurance industry.
Individuals with questions or seeking further information may contact the Department at insurance@ct.gov or 860-297-3900.
Connecticut is fifth, but Michigan has been first for five consecutive years in an annual comparison of car insurance rates. Connecticut is 34 percent more expensive than the national average, according to the criteria used in the state-to-state comparison.
When the website insure.com looked to compare car insurance rates, they worked with Quadrant Information Services to calculate car insurance rates for a 40-year old man seeking full coverage from six different major carriers. They tabulated the price quoted in 10 zip codes for every state, looking for the average of a 2018 model-year version of America’s 20 best-selling vehicles.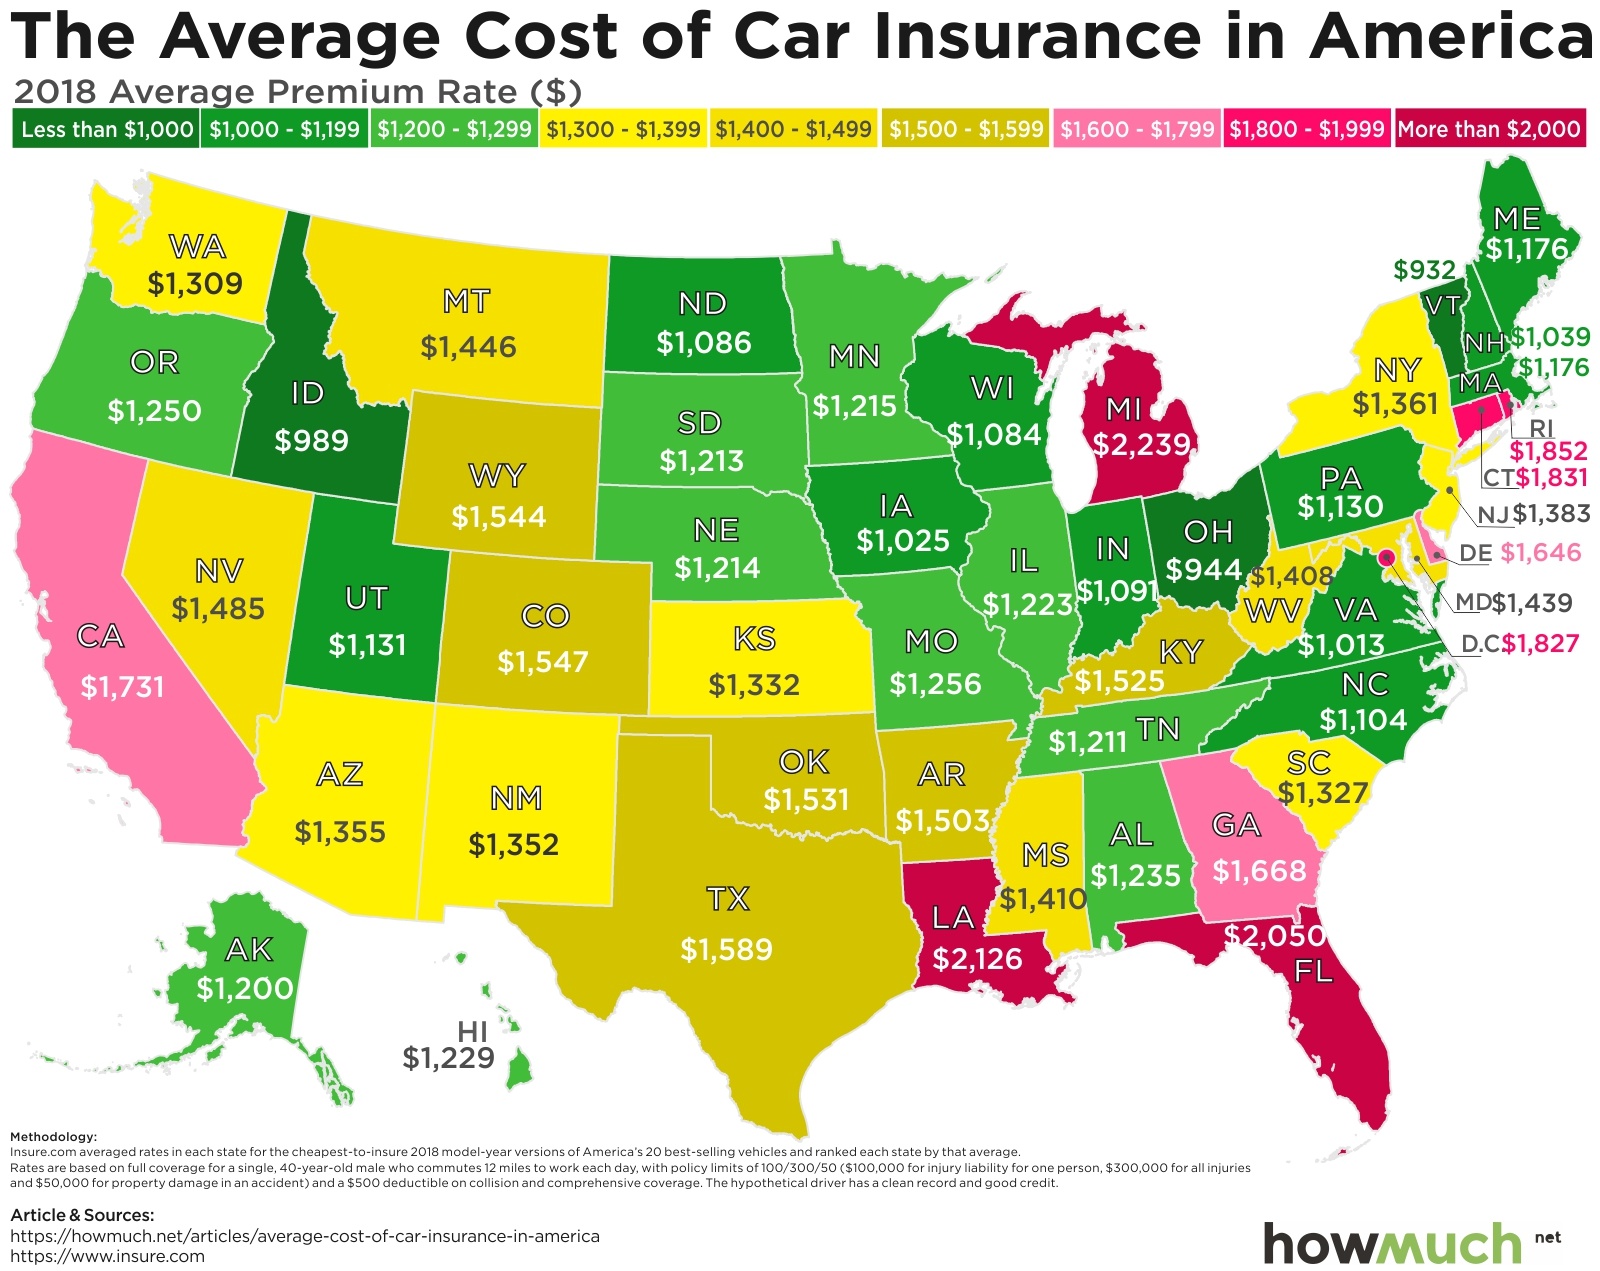
Their finding: car insurance rates can vary widely depending on the state you call home, and numerous other factors. Connecticut was near the top – in the middle of the top ten most expensive states for car insurance, based on this criteria. A year ago, Connecticut ranked third.
The website’s analysis pointed out that high vehicle density is one culprit for higher than average premiums. They noted that Connecticut is the fourth densest state in the country and “tons of cars piled into a small space leads to accidents, which leads to claims, which ends in high car insurance rates.”
The top five states with the highest rates were Michigan ($2,239), Louisiana ($2,126), Florida ($2,050), Rhode Island ($1,852) and Connecticut ($1,831). Rounding out the top ten most expensive states for car insurance, according to the survey, were Washington DC ($1,827), California (1,731), Georgia ($1,668), Delaware ($1,600), and Texas ($1,589).
Across the Northeast, Vermont ranks lowest in the entire country at just $932. New Hampshire was also among the lowest, at $1,039. Massachusetts ranked number 38, with an annual premium of $1,176.
Hartford is surging. So says Inc. magazine, in the latest ranking of the leading “Surge Cities” in the U.S. – the 50 Best Places in America for Starting a Business. Of Hartford, which ranked number 46, the publication said “Hartford gets its groove back by doubling down on manufacturing--and social impact startups.”
Hartford ranked just ahead of Memphis, Cleveland, Virginia Beach and Buffalo in rounding out the top 50. Leading the list were Austin, Salt Lake City, Raleigh, Nashville, San Francisco, San Jose, San Diego, Denver, Orlando and Portland.
Inc. pointed out that “Despite years of state budgetary woes, the Hartford area is on an upswing--thanks, in part, to a rebound in manufacturing. Aerospace company Pratt & Whitney can't keep up with jet engine orders, and Otis Elevator does over $12.3 billion in net sales.” They went on to highlight what’s new: “Pioneering accelerator ReSet, which has a social impact focus, has graduated 100 area companies over the past five years. Toolmaker Stanley Black & Decker recently launched a manufacturing accelerator with Techstars. And Hartford--the ‘insurance capital of the world’--was named one of the state's four Innovations Places, making it eligible for $2 million in matching funds, part of which it's putting toward an accelerator aimed at insurance startups.”
Among the criteria in the analysis, and Hartford’s ranking: rate of entrepreneurship (38), high-growth company density (48), net business creation (35), early-stage funding deals (35) and wage growth (21).
Elsewhere in New England, Boston ranked number 15; Providence was number 44.
With the ghosts of Hartford Whalers past brought back to life for a one-night stand in Raleigh, North Carolina this past weekend, a glimpse at attendance numbers may give some perspective on what was, what is, and what might have been.
The Carolina Hurricanes home attendance in the 31-team National Hockey League ranks 29th in the league thus far in the 2018-19 season, after 20 home games, not including Whalers night. The team has been drawing considerably better on the road (17,258) than at home (13,245). 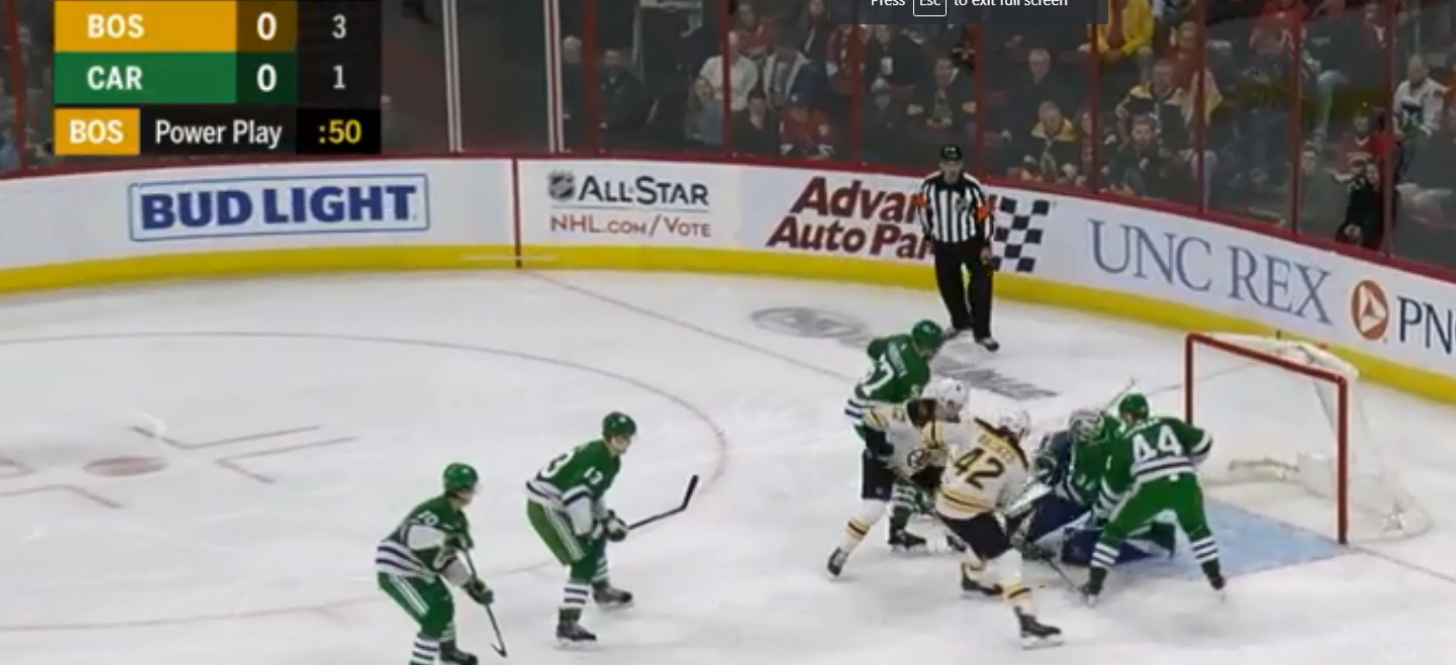
That home attendance figure should come as no surprise. It is on pace for last season’s home attendance average over 41 games of 13,320. Then as now, it was the third lowest home attendance average in the league. Only Arizona and the New York Islanders drew fewer fans to home games.
It’s no wonder that the Hurricanes were seeking to recapture some of that Whalers magic – or should we say Bonanza. And also cash in on merchandise sales, as well as seeking an attendance boost, even if only for a night.
In early 1996, a 45-day “Save the Whale” season-ticket drive in Hartford resulted in 8,300 season tickets sold, about 3,000 more than the previous year. In the aftermath of the season ticket drive, and heading into the 1996-97 season, the Whalers management said they would remain in Hartford for two more years, in accordance with their lease. Yet they ended their 18-year history as the Whalers in Hartford, moving to Greensboro, North Carolina seeking redder pastures and becoming the Carolina Hurricanes for the start of the 1997-98 season.
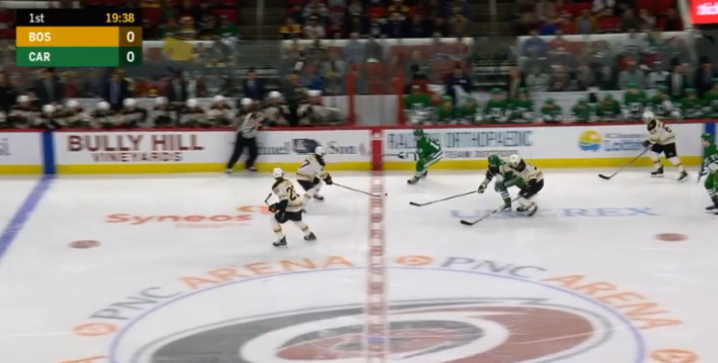 In the Whalers’ final season in Hartford, 1996-97, attendance at the Hartford Civic Center had grown to 87 percent of capacity, with an average attendance of 13,680 per game. Published reports suggest that the average attendance was, in reality, higher than 14,000 per game by 1996-97, but Whalers ownership did not count the skyboxes and coliseum club seating because the revenue streams went to the state, rather than the team. Attendance increased for four consecutive years before management moved the team from Hartford. (To 10,407 in 1993-94, 11,835 in 1994-95, 11,983 in 1995-96 and 13,680 in 1996-97.)
During the team’s tenure in Hartford, average attendance exceeded 14,000 twice – in 1987-88 and 1986-87, when the team ranked 13th in the league in attendance in both seasons. The Hurricanes had somewhat higher attendance numbers in the immediate aftermath of winning the Stanley Cup a decade ago, but they did not sustain those levels and were among the top half of NHL teams in attendance only once.
Keep in mind that as we approach 2019, after two decades in North Carolina, the Hurricanes are only a couple of seasons removed from the recent low water mark in NHL attendance. In the 2016-17 season, the average home crowd was the lowest in the NHL – only 11,776. It was the second consecutive season that the Hurricanes had the league’s worst home attendance numbers. (They were second worst the previous year.)
The Hurricanes/Whalers will next skate in Boston against the Bruins in early spring, taking to ice in the green uniforms originally worn as road uniforms by Hartford from 1985-89, then again in 1991-92. The Whalers, by the way, are now undefeated this season, as the Hurricanes defeated the Bruins 5-3 on Sunday afternoon. The win was not without criticism, with one published report describing the Hurricanes new first-year management as leading "the desecration of a grave and a shameless ploy to drum up some jersey and merchandise sales. A cash grab."
The crowd was, as CBS Sports phrased it: "much bigger than they’re used to": 17,491.
https://twitter.com/twitter/statuses/1076998933707177986
Under state law, sexual harassment in the workplace is prohibited as a discriminatory employment practice. As such, violators may be subject to both civil and criminal penalties. In addition to the anti-discrimination statutes, laws regarding sexual harassment also appear in statutes
Read MoreConnecticut Attorney General George Jepsen has initiated a lawsuit against Stamford-based Purdue Pharma and several current and former members of Purdue's management and board of directors alleging that they designed, financed and waged a pervasive and aggressive campaign to mislead doctors and patients, claiming that prescription opioid medications manufactured and marketed by the company were safe and effective and strategically downplaying risks of addiction that they knew were inherent in their opioid products.
 The state alleges that Purdue "peddled a series of falsehoods" to push patients toward its opioids, reaping massive profits from sales while opioid addiction skyrocketed to the crisis level that is currently impacting Connecticut and states across the country.
"For a number of months, Connecticut and our multistate partners have been engaged in intensive negotiations with opioid manufacturers and distributors in the hope of resolving potential legal claims in a way that would avoid protracted litigation and would bring opioid treatment resources to those who are desperately in need," said Attorney General Jepsen. Jepsen, who leaves office next month, currently serves as part of the leadership of a multistate coalition of attorneys general who are investigating opioid manufacturers and distributors. "I expect those negotiations to continue, and I remain hopeful they will bring a resolution that helps to address this ongoing crisis."
In Connecticut, 1,038 people died of accidental drug overdoses in 2017, the vast majority from opioid-related overdoses. The Connecticut Office of the Chief Medical Examiner has projected that 1,030 more people will die of overdoses in 2018. From 2013 to 2016, Connecticut experienced a fourfold increase in deaths from prescription opioid overdoses, and the estimated economic cost of the opioid epidemic in Connecticut in 2016 was $10.27 billion. Nationwide from 2002-2017 there was a 4.1-fold increase in the total number of deaths involving opioids, according to the National Institute on Drug Abuse. 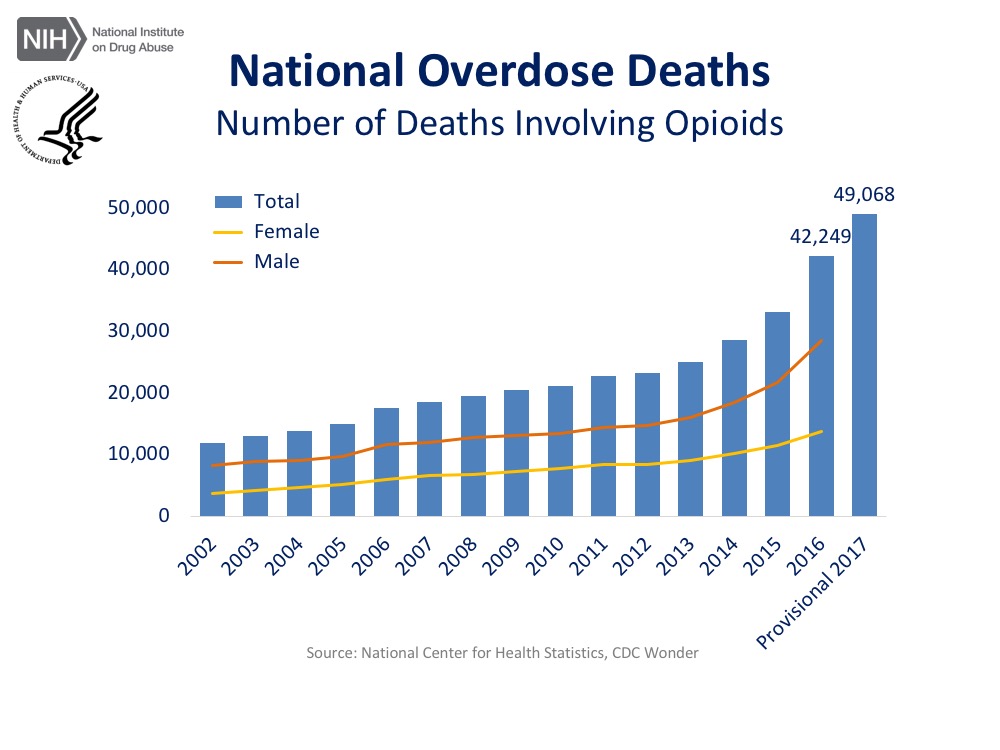
The Attorney General said that Purdue Pharma “has not demonstrated to me that it is serious about addressing the states' very real allegations of misconduct and coming to a meaningful settlement. It is my hope that, in filing this lawsuit at this time, Connecticut can assist in the collective effort to hold this company and responsible individuals accountable.
Jepsen said the state alleges that “Purdue knowingly put its own exorbitant profits first when it purposefully and systematically misled doctors by not just downplaying the terrible risks of addiction, but by forcefully asserting that opioid products were safe, that the risk of addiction was low, and that patients experiencing symptoms of addiction should actually be prescribed higher and greater doses of Purdue's opioid drugs. We allege that this behavior was endorsed and promoted by the highest leadership of the company and that it was in violation of Connecticut law."
The state alleges that Purdue misinformed patients and doctors to get more and more people taking its premier opioid drug, OxyContin, and its two other opioid medications, Hysingla and Butrans.
The lawsuit will be filed in Superior Court in Hartford. It alleges four counts of violations of the Connecticut Unfair Trade Practices Act and seeks damages, civil penalties, forfeiture of ill-gotten profits and restitution as well as permanent injunctive and other relief. The suit indicates that Purdue allegedly:
The company did not tell doctors that higher doses of opioids carried heightened risk of addiction, overdose and death, the state alleges, and the company funded and distributed publications that misrepresented the addictive nature of prescription opioids and made claims that were not supported by scientific evidence.
The state further alleges that Purdue promoted the idea of "pseudoaddiction," suggesting that patients who appeared to be addicted were instead receiving inadequate doses and needed more prescription opioid drugs.
In addition to the company, the state's lawsuit names current and former board members as defendants, alleging that they tracked sales representatives and oversaw the tactics used to push opioid drugs. The individual defendants include: Richard Sackler, Jonathan Sackler, Mortimer D.A. Sackler, Kathe Sackler, Ilene Sackler Lefcourt, Beverly Sackler, David Sackler, Theresa Sackler, Cecil Pickett, Paulo Costa, Ralph Snyderman, Frank Peter Boer and Judy Lewent. The lawsuit also names past CEOs John Stewart and Mark Timney as defendants.
Attorneys for ratepayers, efficiency businesses and environmental organizations have filed an appeal in the U.S. Court of Appeals for the Second Circuit in New York , asking the appellate court to reverse an October 25 U.S. District Court decision that denied plaintiffs a remedy in their lawsuit to force the State of Connecticut to restore $145 million in ratepayer dollars intended to save families money on energy bills and reduce climate pollution.
The original lawsuit, filed in May, was filed to stop the state legislature’s 2017 sweep of Connecticut’s energy efficiency and clean energy funds, and to prevent future diversions of ratepayer funds. The original complaint argued that diverting ratepayer funding to plug a budget deficit instead of using the dedicated funds for its intended purpose violates the Contract Clause and Equal Protection Clause of the United States Constitution and functions as an illegal tax on tax-exempt organizations like churches and nonprofits.
“We are pursuing the case to fix the damage the raids have done to Connecticut families and businesses,” said Roger Reynolds, chief legal director at Connecticut Fund for the Environment. “Residents trusted that their ratepayer dollars would go where their electric bills said they would—towards energy efficiency and clean energy programs that save money and cut climate pollution. Instead those hard-earned dollars were used to plug a hole in the state budget. We believe the appellate court will see that the state’s action violated federal contract and tax law, and ask them to correct that mistake to put Connecticut back on the path to a healthier energy future and a stronger economy.”
Judge Janet C. Hall at the U.S. District Court in New Haven ruled in October that the state’s 2017 budget that swept ratepayer funds did not impair contracts between ratepayers and their electric distribution companies because neither utility tariffs nor state law ever promised ratepayers that their dollars would not be transferred to the General Fund for unrelated purposes.
The organizations filing the suit pointed out that when the General Assembly found itself facing a deficit in fall 2017, they passed a budget instructing the state to “sweep” and divert the energy efficiency and clean energy funds to the general fund. However, these funds are not government property, they stressed, and were not raised through state taxes but were paid by ratepayers to utilities for specific services. Therefore, "seizing these funds amounts to taking ratepayer funds that were paid for another purpose."
As a result of the "raids", the filers of the lawsuit pointed out that "12,900 homes will not receive energy assessments, weatherization upgrades, reduced pricing on insulation, or associated energy bill savings. Furthermore, 5,600 of these are low income households that often require additional financial assistance to close the energy affordability gap. The award-winning Connecticut Green Bank leverages $6 in private investment for every $1 of renewable energy funding. Yet these sweeps resulted in a 53% reduction in this program’s budget, requiring layoffs and project cancellations."
This case raises an important legal issue relevant beyond Connecticut, according to environment groups, because it is the first time ratepayers argued in court that when they pay their utility bills with surcharges dedicated for specific programs or services—such as energy efficiency and renewable energy—enforceable contracts arise that cannot be invaded by any state.
"Connecticut’s leaders broke the trust of their constituents when they turned electric ratepayer dollars into an illegal tax,” said lead plaintiff Leticia Colon de Mejias, chair of Efficiency For All (EFA) and founder. “Even in these difficult times, it is obvious that stealing ratepayer funds intended to help Connecticut residents and businesses reduce energy waste, save money on energy bills, and access clean resources is a bad choice."
“Sierra Club Connecticut supports this legal appeal by Connecticut Fund for the Environment and allies, and the advocacy of groups including Efficiency for All, to restore the misappropriated energy efficiency monies that our General Assembly voted to take away and use as a stop gap for our budget woes" said Martha Klein, chair, Sierra Club Connecticut. "It was a myopic mistake, as these funds have been proven to create jobs, make revenue for the state, and reduce climate-destroying greenhouse gas emissions. This type of fund raiding hurts all of us in the long run. That money was taken from ratepayers specifically to improve the efficiency of our whole state, which would save all of us money on energy costs, and improve our health and climate.”
When the initial suit was filed against the state back in May, Governor Malloy issued a statement that, rather than defending the state action, seemed to take the opposite view:
"This should come as a surprise to no one. I have long maintained that these shortsighted sweeps would increase energy costs for consumers and businesses and cause untold harm to our green energy economy. [W]e should be cementing our role as a national leader in our efforts to combat climate change and protect our communities. The energy sweeps . . . represented a massive step backwards, and I continue to strongly oppose them," Malloy said.
by Sunil Bhatia I would like to begin by sharing with you some reflections on my summer reading.
I read a New York Times article about children who were separated from their parents at the U.S. border. Leitica, a petite, 12-year-old girl from Guatemala and her younger brother, Walter, were separated from their mother when they crossed the border without documents. These siblings were sent to a detention facility in Texas, which has a list of several rules that these young migrants must follow, “Do not misbehave. Do not sit on the floor. Do not share your food. Do not use nicknames.” The detention center also included this rule, “It is best not to cry. Doing so might hurt your case.” “Do not touch another child, even if that child is your hermanito or hermanita–your little brother or sister.”
Another child requested her lawyer mail a letter to her detained mother, with whom she had been separated for over three weeks. The girl wrote, “Mommy, I love you and adore you and miss you so much.” And then she pleaded: “Please, Mom, communicate. Please, Mom. I hope that you’re OK and remember, you are the best thing in my life.”
Leticia and her brother belong to over 65 million refugees and migrants worldwide who are displaced and are in harm’s way. After overcoming the perils of leaving home and embarking on an uncertain and often dangerous journey, they cross the border only to be treated as unwanted and inhuman others.
The story of Leticia and Walter haunted me.
I wondered when they would reunite with their mother.
Then I read the Pakistani author Mohsin Ahmed’s book, Exit West. The story focuses on Saeed and Nadia, whose love story unfolds in a nameless city that is filled with refuges and is teetering on the edge of war. Saeed and Nadia’s courtship speeds up against backdrop of raids, rocket fire, truck bombs and the constant noise of helicopters and drones that hover over the city. Their city gradually becomes unlivable. The government collapses, the militia take over the city, and the threat of violence is around every corner.
Suddenly there are rumors in their city that there are doors that open up to other countries. These trickster doors are like black holes or rips in reality that transport people across to countries and spaces of relative safety in an instant. Saeed and Nadia escape their city through these magical doors that eventually takes them to Greece, London and then to California.
Forgive me for getting seduced by the magical realism of this gorgeously written novel. But all summer, I have been hoping, rather dreaming, that Leticia and her brother find a magical door that takes them out of the cold and grotesque reality of detention centers in Texas and reunites them with their mother.
I have been dreaming that all families separated by migration have access to those doors that takes them to places, where they are loved, and can live fulfilling lives.
Alas, we know, there are no such mystical doors.
But think again.
I believe the magical realism of supernatural doors in Ahmed’s novel is not only about physical borders and doors. It is really about opening up the reader’s imagination and making them connect with people who are different from us. The magical doors are a metaphor that represent our human abilities to imagine and empathize.
Ahmed shows us a future world that is on the move because the greater portion of humanity is ravaged by economic inequality, war, extreme poverty and climate change.
He tells us that there is a possibility that every one of us can become a refugee.
 The author asks us to imagine: what if the College Green where we have assembled on today becomes a tent-city for us refugees next week? Would you close the doors on migrants and refugees if you knew that one day you too would become a migrant? Would you call migrants animals and rapists if your destiny was linked with their lives?
Our ability to imagine a different world than the one we have been given is our magical door. Some people are looking for actual doors that give them entry into new countries and spaces and some others are entering through a figurative door.
Sometimes both are needed for making sense of our life journeys.
My Journey Here
I found my magical door over 25 years ago when I made a journey that is very similar to the freshman Class of 2022.
I left my home from Pune, India, and travelled to the U.S. to become a graduate student at Clark University, a liberal arts school, in Worcester, Massachusetts. Like many international students from my era, I carried a suitcase with my precious belongings: photographs of my father and mother taken at a studio, farewell photos with my friends, Hindi film music, my best ever report card from 6th grade when I stood third in class, boxes of tea leaves, recipes, and small bags of turmeric, cumin, and coriander powder.
My first week or rather the first year in this new world was disastrous. I was so fresh off the boat that when my American friends greeted me with, “How are you?” I poured my heart out and told them my life story. I had missed the cultural point that a greeting is just a means of making polite talk. Instead of talking about the weather, I told strangers how I missed home, my family, friends and the smells of Indian streets.
My life was downright pre-historic compared to the Class of 2022. Every week I would handwrite dozens of letters home to my friends and family telling them about my life in America. Then an Indian owl would travel thousands of miles to Worcester and drop letters from home in my mail box. Well, the Owl bit may be exaggerated.
I was not fleeing a war zone or poverty, but yet I experienced a displacement that comes from being uprooted from home. Crossing borders brought pain and anxiety about the world I had left behind and the future that was yet to unfold. With time, I found a way to settle in the new world of American university life. Life at the university was fulfilling, but when I left the campus to go back to my apartment I witnessed another America.
This was an America segregated from the campus by just one street. Coming into my neighborhood in South Main in Worcester was like crossing a border or entering another country. The homes were crumbling, the schools were failing, and the old factories and mills had been abandoned. The university warned us about the dangers of South Main and we were told to avoid walking at night as it was filled with “dangerous people.” These so-called dangerous people bore a resemblance to my people back home–they were mostly brown, immigrants, the invisible and the poor.
One day, during summer, I went to a local bar to play pool with friends. When I moved close to the pool table, one of the local white youth told me to leave with the following words: “We don’t play with no Puerto Ricans. They are not wanted here.” Being called Puerto Rican was not about mistaken identity–it was a racist gesture.
I sensed an impending threat of violence. I left the bar. That day I went from being an international student to an immigrant and a person of color.
This was an important turning point in my journey.
I felt humiliated and reflected on this and similar incidents that I had previously chosen to ignore. I was an outsider to the American racial formation so I had the privilege of disregarding racism. This is what racism does to people. It shames them, makes them feel inadequate, and silences them. The experience of racism creates doubt and makes you believe that your story could not be true.
I was a newcomer to racism. I was a newcomer to segregation.
African-Americans had been here long before me for centuries fighting racial terrorism and resisting racism. Their inner lives are an inspiring tribute to the enduring spirit of humanity. I soon realized my new home and university was once the home of the Nipmuc Indians. Their land was stolen, their lives were destroyed and their culture was frozen in history.
My racial awakening made one thing clear to me: Whiteness served as a powerful norm, but its power was rarely interrogated. When I overcame my fear and questioned whiteness, I was often met with indifference or anger. It was only much later in life, when I encountered the term “white supremacy” that I fully understood how deeply whiteness had become integrated into everyday living and structures of American society: courts, schools, law, medicine, media, higher education, and politics.
My racial consciousness taught me something deeper. Whiteness had largely reinforced a narrative that people of color had a deficient humanity, they did not belong in this country, and their stories did not matter in the media or the curriculum. When people from marginalized communities showed up in the books I was reading, they often served as caricatured props and tokens for advancing the cause of whiteness or as victims that needed to be saved.
The psychology I had encountered in my graduate school in India and the U.S. was largely built on colonial knowledge, universalistic principles and Eurocentric cultural assumptions about individuality and rationality. It was a psychology based on 5 percent of the human population but yet it had the power to speak on behalf on the 95 percent of humanity.
There was something wrong with this picture.
I did not find my story in the canons of psychology so I wanted to tell a different story of psychology. I challenged psychology’s claims of universalism and its refusal to acknowledge history, culture, and politics.
I failed several times to articulate my vision of psychology. But reading books, doing research, engaging in teaching, and having conversations with a community of learners became my enchanted doors.
To put it simply, I found the tools to make sense of my emotional and intellectual life.
My education in a liberal arts university was a gift. My research focused on understanding how migrants, who have never thought of their identity in racial terms, become people of color in the United States.
My biography in America became the basis of my research. My first book, American Karma, and my early publications, drew on anti-colonial and anti-racist frameworks to challenge the universality of longstanding racial and ethnic assimilation models in psychology and human development.
Turning Point
9/11 marked another turning point in my career.
Immediately after 9/11, I was conducting ethnographic research for my first book. During an interview, a Sikh man, who worked as a high-level scientist for a local company, told me that he had not stepped outside for a week. He was afraid of being a target of a hate crime, so his wife did the groceries.
When I arrived at his home, he was in the middle of a family meeting discussing whether he and his son should cut their hair, beard, and if they should stop wearing their turban because it brought unwanted attention.
I did research on the changing notions of cultural citizenship and racial identity formation driven in large part by Islamophobia. I examined how the Sikh American community with their turbans, beards and their “brown identities” had become suspect in the larger American public space. They were framed as outsiders and turned into targets of racial profiling, scrutiny, and hate speech.
Since then I have continued my quest to radically transform my field. In my latest book, Decolonizing Psychology, I write about the shaping of Indian youth identities within the context of globalization, colonization, and neoliberalism. By focusing on the lives of youth in the Global South, I challenge Euro-American scientific psychology to recognize its own limits and to become more inclusive, reflexive and relevant to the majority of humanity.
Looking back, I can tell you that I am standing up here and sharing my story with you because I had access to a liberal arts education. Yes, that education gave me a livelihood, but what is even more remarkable is that it gave me meaning and purpose in life. Every major milestone in my career was achieved because I had support from colleagues, family, and community.
For over two decades now, my classroom has become my dwelling and my research is my imaginary homeland, and it is from these spaces my students and I together go out searching for those magical doors.
Your Journey Begins
Class of 2022, I know that like my own journey you too will cross several imaginary, physical, and conceptual, borders and you will experience many crucial turning points in your education. Your story, your journey and your discovery will be different than mine.
You have arrived on this campus to commence a new term and a new stage of life, but your racial, ancestral, sexual and cultural histories that brought you here are complex and diverse. For some of you, this College reminds you of home. You may feel you belong here. You have found your place. For some others, you may feel out of place and even out of your mind.
Use your time here at the College to make sense of your identity and the structures that shape your evolving self. Try to connect your story to people like Saeed, Nadia and Leticia and other people you have not yet met. Those characters don’t just live in fiction, detention centers, and brochures. You will find that brown, black, lesbian, gay, bisexual, transgender, queer or questioning, intersex, asexual or allied, heterosexual, cisgender, native, white, Asian, biracial, immigrants, international, local, and first-generation, members live in this community. You will meet them in your classrooms or at Harkness, Windham, Coffee-Grounds and Harris.
Your journey here is not a solo expedition. Rather you will be building community with these diverse members and you will collectively work towards transforming this institution. The word “liberal” in liberal arts is derived from the Latin word “liberalis,” which means to be free or a free-thinking person. The right to dissent and protest in the in the pursuit of learning to become a critical and free thinker is at the heart of a liberal arts education.
James Baldwin, an African American novelist and social critic, reminds us that the true “nature of society is to create, among its citizens, an illusion of safety.” So, if your belonging in the community feels like an illusion or makes you feel unsafe, he says, go ahead and use nonviolent means to disturb the peace to make it equitable and inclusive.
 Think about this for a moment, Class of 2022. You have already witnessed in your lifetime such powerful attempts to break the illusion of safety: The resistance offered by the birth of Black Lives Matter, the rise of the MeToo movement, the constitutional rights accorded to same-sex or gay marriage and the example of solidarity shown by the native people of Standing Rock in the face of oppression. The people behind these nonviolent movements were imagining a different world and a different community than the one they have been given. Their struggle for justice and belonging opened up new magical doors so others could step in, rise up, feel loved, and know that their lives matter equally in this society.
What these big and small stories of social change tell us that a liberal arts education is more than employability and building a career. It is about cultivating humility, empathy, creating community, and practicing what Sikh American civil rights activist Valerie Kaur calls “revolutionary love.” She says, “Revolutionary love is the choice to enter into labor for others who do not look like us, for our opponents who hurt us and for ourselves.”
I believe cultivating critical thinking along with the capacity for revolutionary love is one of the most important projects of a liberal arts education.
Engaging with this form of education can give you knowledge needed for writing poetry, fighting for social justice, carving out your belonging, countering fake news, studying abroad, learning a new language, becoming a teacher, psychologist, scientist, sociologist, engineer, historian, artist, dancer, or a philosopher.
That is all you will need to soar high.
_________________________________
Sunil Bhatia is Professor of Human Development at Connecticut College in New London. This is an excerpt of the address he delivered at the college's Convocation at the start of the current academic year on August 27, 2018.






© 2026 Connecticut By The Numbers [TM] 557 Prospect Avenue - 1st Floor, West Hartford, CT 06105
Designed by RDK Design & Photography